











Retail POS System: How to Choose Types, Fees and Software
A retail POS system is the combination of hardware, software and payment processing that closes a sale in a physical store. EU Regulation 2015/751 caps interchange at 0.2% for consumer debit cards and 0.3% for consumer credit cards, yet flat-rate providers bill the same 1.65% to 1.75% on every card: that gap is where a store with 20,000 euro per month in card volume leaves real money. This guide breaks down POS system types, fee models and integration choices for retail, with worked cost examples.
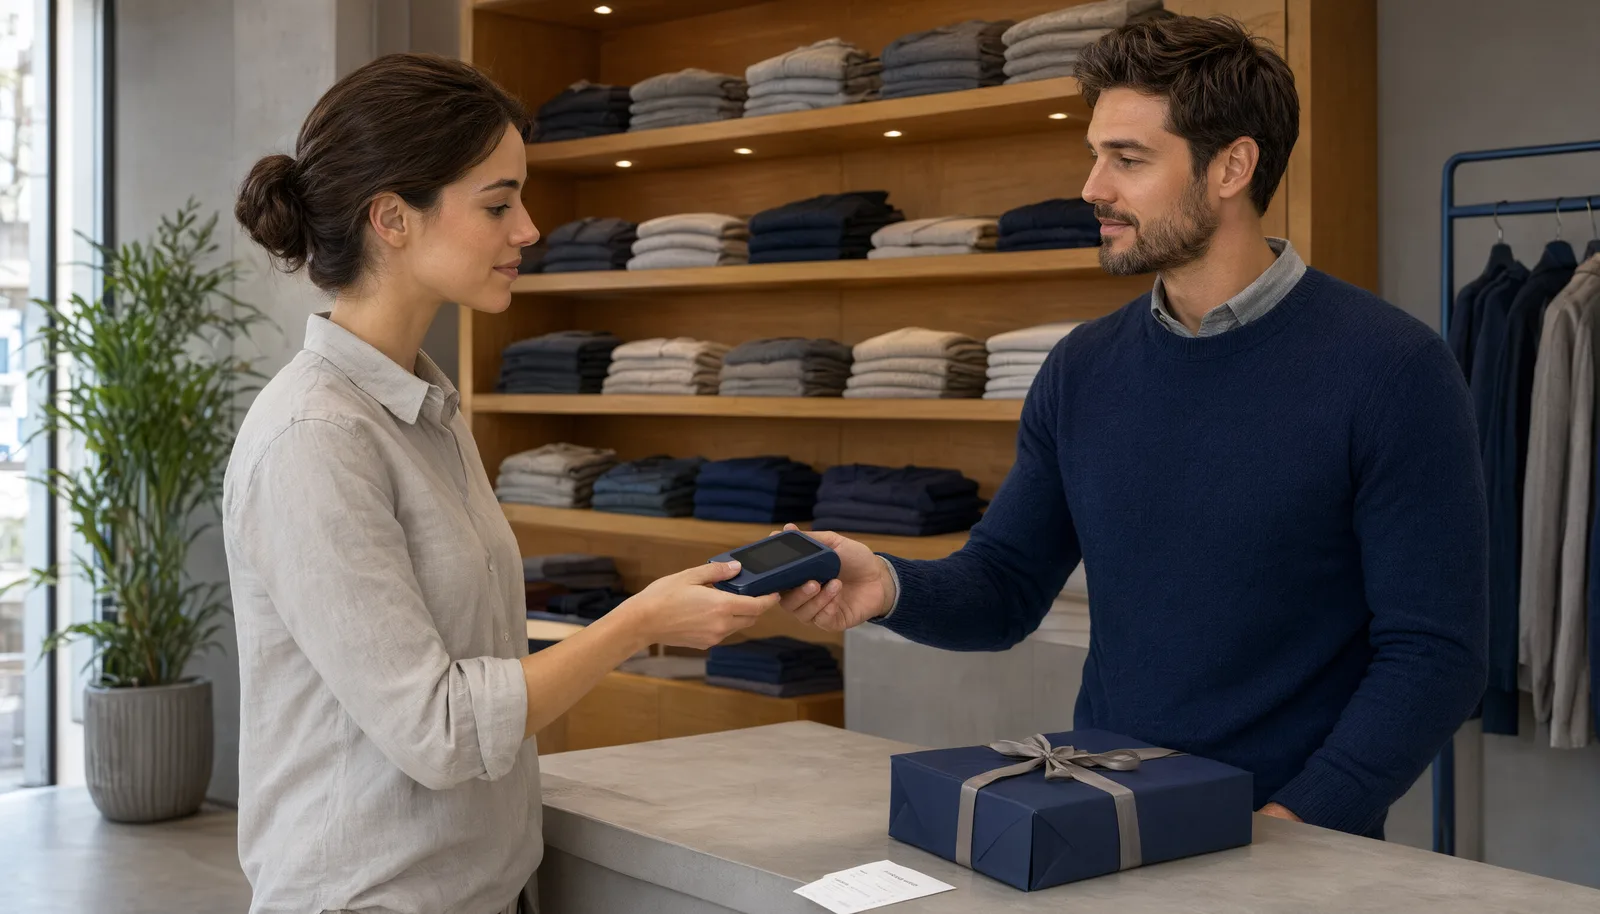
What a Retail POS System Actually Includes
A complete retail POS system has three layers, and shops that compare only the hardware routinely pick the wrong one.
Terminal hardware: pinpad, contactless reader and printer (fixed counter terminals, Android smart terminals, or Bluetooth readers paired with a phone).
POS software: the catalog, receipts, refunds and end-of-day reports. When this layer runs inside a wider cash management suite it becomes an EPOS, so stock, loyalty and payments stay synchronised.
Payment processing: the merchant account and acquiring that actually move the money. Processing is the layer that repeats on every sale, so on 20,000 euro per month the processing fee difference of even 0.4% is 80 euro per month, every month, while hardware is a one-off cost of a few hundred euro.
Retail POS System Types and When Each Fits
Fixed counter terminal: the standard for shops with a single checkout lane (apparel, electronics, cosmetics). Reliable, cheapest to run per transaction at the counter.
Android smart POS (portable): staff take the payment to the customer in the fitting room or on the showroom floor; a 4G model keeps processing through network outages and syncs when the shop WiFi returns.
Bluetooth mobile reader: for markets, pop-up stores and itinerant sellers; for phone orders a virtual POS on a laptop covers the same need without any extra hardware.
EPOS with integrated payments: chains and multi-register stores run payments inside the cash management software so every register posts into one report. Multi-register stores should confirm that all terminals roll into one settlement file before signing.
Retail POS System Fees: Flat Rate vs IC++
Flat-rate providers bill the same percentage on every card: SumUp charges 1.69%, Square about 1.65% and PayPal 1.75%. Simple to read, but it ignores what each card actually costs: an EU consumer Visa Debit carries roughly 0.2% interchange under the EU caps, while premium credit tiers carry 0.30% and up.
IC++ (interchange++) bills the real interchange of each card plus a fixed markup, so a debit-heavy shop pays debit prices instead of a padded flat estimate.
RoxPay: €0.15 + 0.35% to 0.85% (IC++). On 20,000 euro per month with a 65% debit share, a flat 1.69% costs 338 euro; the same volume on per-card pricing with a low-interchange debit mix lands well below that, typically 30% to 40% less, because the fee follows the actual cost of each card. For the full comparison method, see the [POS costs breakdown](/en/resources/pos-costs-fees-commissions-hidden-charges).
Choosing Retail POS Hardware and Software
Hardware checklist: contactless built in (now the default tap share in EU retail), 4G fallback for outages, and a customer-facing display for premium stores.
Software integration: confirm the POS speaks to your stock system before buying: Lightspeed and Shopify POS-class environments are the two most requested, and regional EPOS suites usually integrate through an API or plugin.
Card acceptance: Visa, Mastercard, Amex and international schemes belong in the standard range; refusing Amex loses the whole basket, not just the fee.
For a type-by-type hardware decision matrix, the [best POS for retail guide](/en/resources/retail-pos-guide) compares counter, mobile and EPOS setups with fee examples on real volumes.
Common Mistakes When Switching Retail POS System
Signing on the headline rate: a flat 1.69% looks simple, but without a card-mix estimate nobody knows what the shop is actually paying versus per-card pricing. A 0.2 percentage point gap on 20,000 euro per month is 40 euro per month, 480 euro per year.
Buying hardware before checking software: the terminal must talk to the stock system; if integration only exists through a manual CSV export, the till and the inventory drift apart within weeks.
Ignoring statement detail: scheme fees and cross-border surcharges are itemised separately from the headline rate; read one full statement before renewing any contract.
Cutting over in peak season: switch systems in the quietest trading week, keep the old terminal live until the first settlement of the new one has cleared, and test refunds on a real transaction, not in a demo environment.
Rollout Checklist for a New Retail POS System
Before activation: business registration documents, payout bank account, and a card-mix estimate (share of debit vs credit, domestic vs international) so the fee model is chosen on real data, not on a brochure.
On site: test every payment method at the counter (chip, contactless, wallets, refunds), confirm the printer and till roll setup, and train staff on voids before settlement and refunds after settlement.
After go-live: settlement should land within 48 hours to any SEPA bank; if the first payout takes longer, escalate immediately. Review the fee statement after the first full month against the card-mix estimate from step one.
Questions fréquentes
How much does a retail POS system cost per month?
There are two components: hardware (a one-off purchase or a rental) and processing fees charged on every transaction. On 20,000 euro per month in card volume, a flat 1.69% model costs about 338 euro in fees, while per-card IC++ pricing on a debit-heavy mix typically costs 30% to 40% less. Hardware and rental trade-offs are compared in the [POS rent or buy comparison](/en/resources/pos-rent-vs-buy-which-is-better).
Is a retail POS system the same as an online payment gateway?
No: a retail POS system handles face-to-face payments at the counter, while an online store needs a [payment gateway integration](/en/resources/payment-gateway-integration) for checkout payments. Unified commerce setups run both on one account so sales, refunds and reports stay in one place.
Can one retail POS system run online and in-store sales?
Yes, if the POS software synchronises with the online catalog: the terminal folio and the webshop share one stock count, and refunds made in-store show against the online order. Verify the sync is real-time or end-of-day, because a stock mismatch creates overselling.
Does every store need the same terminal type?
No. A single-lane boutique runs fine on one counter terminal; a store with high-value products sold on the floor benefits from portable Android terminals; markets and pop-ups work with a Bluetooth reader. Match the hardware to where the payment physically happens, then optimise the fee model.
Vous pourriez aussi aimer
Passerelle de paiement à haut risque
Traitement sécurisé des paiements pour les secteurs à haut risque avec routage multi-acquéreur et protection contre les rétrofacturations.
Solutions de paiement pour petites entreprises
Tarification IC++ transparente, terminal Smart POS gratuit et activation en 24 heures pour les petites entreprises.
Intégrations de paiement e-commerce
Plugins en un clic pour WooCommerce, Magento et PrestaShop avec accès API complet.
Optimisez vos paiements dès aujourd'hui
Discover the RoxPay POS for your retail store. No fixed monthly fee, transparent IC++ pricing. Contact us on /en/contact.
✓ Aucun coût fixe mensuel · ✓ Activation en 24 heures · ✓ Support technique dédié
